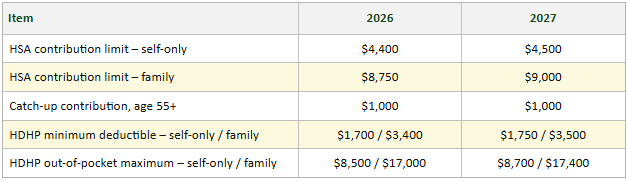
What an exciting time of year! My wife is planting bulbs and I am considering this fall’s leaf pick-up and gutter cleaning strategy, which has gotten easier since she barred me from getting up on the roof anymore. College football is in full swing, which means Holden’s Saturdays are SEC-filled whether at Williams Brice Stadium or a bar with friends. Thanksgiving is in a few weeks. The Hunter’s Moon this morning was spectacular. There is a refreshing chill in the air and daylight savings is this Sunday…
And if that isn’t enough… it is also that time of year when the various retirement plan limits and inflation adjustments such as that for Social Security are announced!
Attached you will find a reference sheet pertaining to retirement plans-only. For employer-sponsored retirement plan participants, you may want to set your January 2027 reminder to adjust your employee deferral amount in accordance with these limits. If you are a high earner doing the catch-up with your current employer, please note in your reminder that you will want to distinguish that the catch-up is in Roth dollars. This has caused confusion amongst plan participants and sponsors this year as it is a new rule and payroll technology is shockingly laggard in accommodating the change.
Below are additional data points we thought you might also be interested in. Our retirees watch the Social Security and Medicare adjustments closely. Our clients that utilize their Health Savings Account (HSA), be it to consume or use as a savings and tax deduction vehicle, should adjust their HSA contribution for the increased limits in January.
Please note 1) we have identified below and in the attachment what data points are confirmed versus only estimates at this point, and 2) we are not tax advisors so cannot recommend tax strategies based on the provided information but are happy to discuss.
Hope you enjoy this reading as much as you do your favorite aspects of fall.
Best Regards,
Geoff
Social Security
Official – announced by the Social Security Administration, October 2026
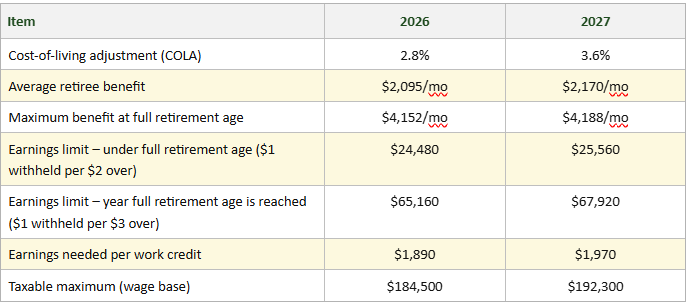
It is becoming common for people in traditional retirement years to continue working out of need or simply a desire for extra spending money while preserving savings. If claiming Social Security before full retirement age, you should review earnings against the new $25,560 limit.
Medicare (Estimate)
2027 figures estimated – based on the 2026 Medicare Trustees Report; CMS typically announces in mid-November.
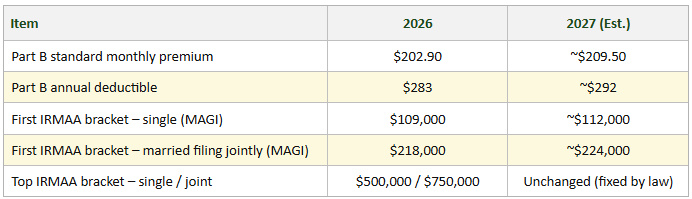
IRMAA is based on modified adjusted gross income from two years prior: 2027 surcharges use 2025 income. Clients with a qualifying life-changing event (e.g., retirement, death of a spouse) may request a reduction using Form SSA-44.
The 3.6% COLA stated in the top table will be partly offset by the higher Part B premium, which is deducted directly from benefits.
Remember that Roth conversions, large capital gains or other income recognized in 2025 may affect 2027 Medicare premiums. IRMAA appeals are available for qualifying life-changing events such as retirement.
Income, Gift and Estate Tax (Estimate)
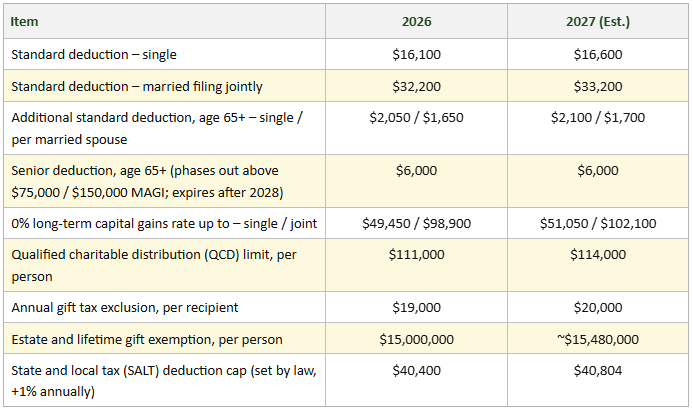
2027 figures estimated – based on Bloomberg Tax projections and the inflation formula in the tax code.
Health Savings Accounts
Official – IRS Rev. Proc. 2026-24