FPFA Monthly Insights – The Midterm Market Outlook (September 2026)
Geoff and I been joking about the mixed reviews from my last newsletter likening an investment portfolio to a set of golf clubs. Could it be that my honeymoon phase at Front Porch Financial has worn off? - maybe. Did I get super excited to tie my love of golf into a work-related topic? - yes. Would Geoff's newsletter idea about how building a portfolio is like managing a garden have been a better analogy? - arguable. Hopefully he wins the coin toss next time so I can take some time to reflect about my future newsletter ideas. Nonetheless, I appreciate all the feedback (good and bad) and look forward to redeeming myself on this month's edition of FPFA Monthly Insights.
Let’s look at the market as it has been a top-of-mind topic with midterm elections upon us with the backdrop of sticky inflation, high oil prices, bond yields soaring, the war in Iran, competing positive and negative economic indicators, etc.
Below is the tale of the tape for the various indices year-to-date followed by midterm market commentary we think you may find interesting.
Relevant Indices Returns' as of 9/23/2026:
DJIA: 7.62%
S&P 500: 12.80%
NASDAQ (Tech): 16.04%
Russel 2000 (Small Cap): 15.06%
MSCI EAFE (International): 11.53%
US Aggregate Bond Index: -1.16%
Q2 of 2026 was the sixth best quarter for a midterm election year. Historically markets have built on such momentum (Figure 1). While stocks were negative in the last 2 midterm election years, there have not been 3 consecutive negative midterm election years in the last 100 years. Although it has not been the case this year, the first three quarters of midterm election years tend to be sluggish and follow with strong Q4 performances when elections take place (Figure 2). Additionally, stocks have had strong average recoveries one year after the max drawdown in the midterm election year (Figure 3).
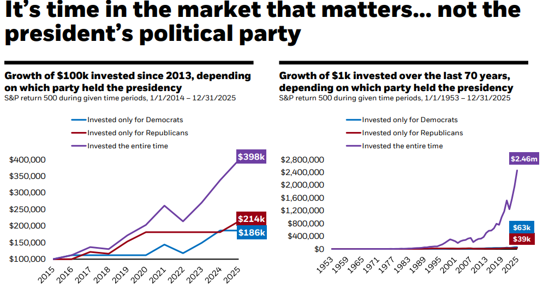
We must emphasize that past performance doesn't guarantee future results. We cannot foresee how the market will react to the upcoming midterm elections and it is important not to focus on short-term swings, but history has shown us that it is not the President’s political party that matters. Rather, it is time in the market that is key (Figure 4).
With an expected voter turnout of 65%, which is much higher than your typical midterm, we expect our clients to have questions about how the elections will affect their investing. Hopefully this data, while not necessarily indicative of what we can expect, illustrates why we might say ‘stick to your knitting.’ Our bias is consistently that you 1) keep money liquid that you may need and consider using us for our money markets and cash equivalents if our rates beat your bank’s, and 2) invest the rest according to our agreed upon game plan. Call us if you want to review that game plan!
Thanks,
Holden
Content referenced is from BlackRock and is not an indicator of future results:
Figure 1
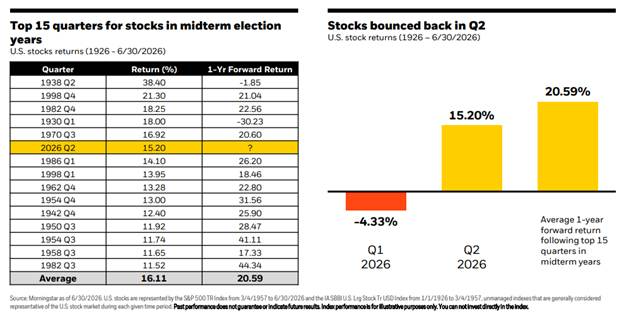
Figure 2
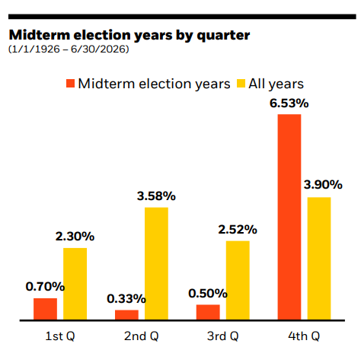
Figure 3
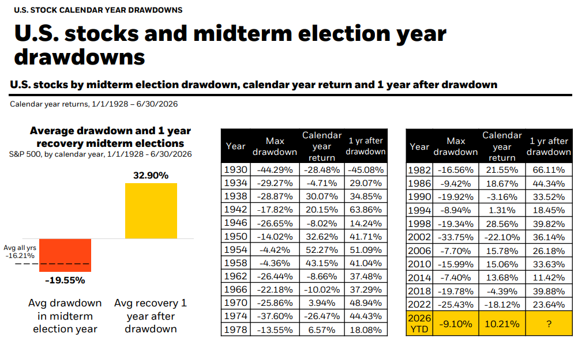
Figure 4